Are Infiniti Q50 Models Really That Expensive to Insure
The Infiniti Q50 is a stylish luxury sedan, but insurance costs can be higher than average. Premiums depend on your model year, trim level, driving history, and location. Understanding what drives Q50 insurance costs helps you make smart choices and potentially save hundreds each year.
Key Takeaways
- Luxury sedans like the Q50 typically cost more to insure due to repair expenses and higher theft risk.
- Model year and trim level play a big role in determining your insurance rate.
- Your personal driving record is one of the most influential factors in your premium.
- Adding safety and anti-theft features can help you qualify for discounts.
- Shopping around and comparing quotes is the single best way to find affordable coverage.
- Higher deductibles lower monthly premiums but increase your out-of-pocket risk.
- Bundling policies with the same insurer can unlock meaningful savings.
📑 Table of Contents
- Are Infiniti Q50 Models Really That Expensive to Insure?
- What Makes the Infiniti Q50 Different From a Regular Sedan?
- How Much Does It Actually Cost to Insure a Q50?
- Key Factors That Drive Up Q50 Insurance Costs
- Tips to Lower Your Infiniti Q50 Insurance Premium
- Common Mistakes People Make When Insuring a Luxury Sedan
- Expert Insights on Luxury Car Insurance
- How to Get the Best Insurance Deal for Your Q50
- Is the Infiniti Q50 Worth the Insurance Cost?
- Final Thoughts
- Frequently Asked Questions
Are Infiniti Q50 Models Really That Expensive to Insure?
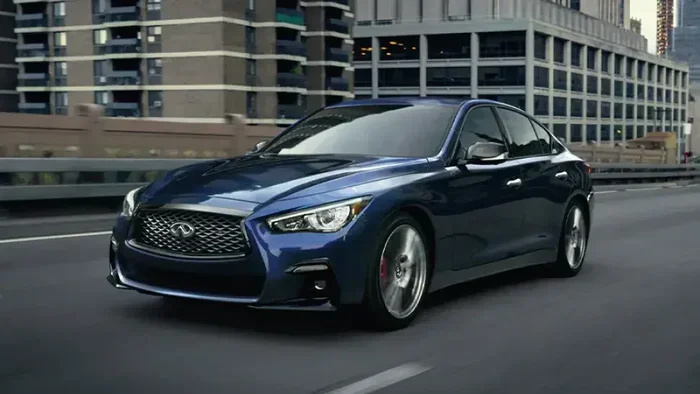
The Infiniti Q50 turns heads on the road. It looks sleek, drives smoothly, and feels premium in every way. But if you are thinking about buying one, a big question comes up: how much will it cost to insure?
Insurance for luxury cars often carries a higher price tag. The Q50 sits in a category where premiums tend to climb. But does that mean it will break the bank? Not necessarily. Many factors determine your final rate, and some of them are entirely within your control.
In this guide, we walk through everything you need to know about Infiniti Q50 insurance costs. We cover what drives the price, how different models compare, and what you can do to save money. Whether you own a Q50 already or are considering one, this article has practical advice you can use right away.
Let us break it down so you have a clear picture of what to expect.
What Makes the Infiniti Q50 Different From a Regular Sedan?
The Q50 is a luxury sports sedan. It stands apart from standard family cars in several important ways. These differences directly affect how insurance companies view the vehicle.
Performance and Power
The Q50 comes with strong engines. Even the base model delivers a solid 208 horsepower. The Red Sport 400 pushes out 400 horsepower. More power often means a higher risk profile in the eyes of insurers. Speeding tickets and aggressive driving tend to correlate with high-performance vehicles.
Repair and Parts Costs
This is a major factor. Luxury car parts cost significantly more than parts for mainstream vehicles. If you get into an accident, repairs on a Q50 can run much higher than on a Toyota Camry or Honda Accord. Insurance companies factor this into their pricing models.
Theft Risk
Luxury sedans attract thieves. The Q50 has a certain appeal on the black market. Higher theft risk translates to higher comprehensive insurance premiums. This is something every Q50 owner should understand.
How Much Does It Actually Cost to Insure a Q50?
There is no single number that fits everyone. Insurance rates vary widely based on many factors. But we can look at general ranges to give you a sense of what to expect.
Average Annual Premiums by Model Year
Older Q50 models generally cost less to insure. Newer models with advanced tech and higher value come with steeper premiums. Here is a rough comparison:
| Model Year | Estimated Annual Premium | Key Factors |
|---|---|---|
| 2014-2016 | $1,400 – $1,800 | Lower value, simpler tech |
| 2017-2019 | $1,600 – $2,200 | Mid-range value, updated features |
| 2020-2024 | $1,900 – $2,800+ | Higher value, advanced safety tech |
These numbers are estimates. Your actual rate could be higher or lower depending on your situation. Always get personalized quotes before making a decision.
How Does the Q50 Compare to Similar Luxury Sedans?
The Q50 competes with the BMW 3 Series, Mercedes-Benz C-Class, and Lexus IS. Insurance costs for these vehicles are in a similar range. The Q50 is not the most expensive to insure in this group, but it is not the cheapest either. It sits right in the middle of luxury sedan insurance costs.
For context, a standard Honda Civic might cost around $1,200 per year to insure. The Q50 typically runs $500 to $1,000 more than that. This premium reflects the luxury status, repair costs, and performance capabilities of the vehicle.
Key Factors That Drive Up Q50 Insurance Costs
Insurance companies use complex algorithms to set your rate. Several factors specifically push Q50 premiums higher. Understanding these helps you know what to expect and how to respond.
Vehicle Value and Depreciation
The Q50 starts at a higher price point than most sedans. A new Q50 can cost between $35,000 and $45,000. Insurance companies base part of your premium on the vehicle’s value. Higher value means higher replacement costs, which drives up your rate.
Depreciation also plays a role. As the Q50 ages, its value drops, and so do insurance costs. This is why older model years tend to be cheaper to insure.
Your Location Matters
Where you live has a huge impact. If you park on a busy city street, your risk goes up. Areas with high crime rates or frequent accidents lead to higher premiums. Rural drivers often pay less than urban drivers for the same vehicle.
Your Driving History
This is the factor you control the most. A clean driving record with no accidents or violations keeps your rates lower. Even one speeding ticket can raise your premium by 20% or more. Insurance companies reward safe drivers with better rates.
Credit Score and Claims History
In many states, insurers check your credit score. A lower credit score can mean higher premiums. Similarly, if you have filed multiple claims in the past, you will likely pay more. Both factors signal risk to the insurance company.
Tips to Lower Your Infiniti Q50 Insurance Premium
The good news is that you are not stuck with high rates forever. There are several strategies you can use to bring down your Q50 insurance costs. Some take a little effort, but the savings are worth it.
1. Shop Around and Compare Quotes
This is the single most effective step. Different insurers price the same vehicle very differently. Get at least three quotes before choosing a policy. Online comparison tools make this quick and easy. You could save $300 to $500 per year just by switching providers.
2. Increase Your Deductible
A higher deductible means you pay more out of pocket if you file a claim. But it also lowers your monthly premium. If you have a good emergency fund, this can be a smart move. Even raising your deductible by $500 can reduce your annual premium noticeably.
3. Bundle Your Policies
If you have home or renters insurance, ask about bundling. Many companies offer a multi-policy discount of 10% to 25%. This adds up fast over the life of your policy.
4. Install Safety and Anti-Theft Features
Modern cars come packed with safety tech, and the Q50 is no exception. Features like blind-spot monitoring, lane departure warning, and automatic emergency braking can qualify you for discounts. Adding an anti-theft device like a steering wheel lock or GPS tracker also helps.
Interestingly, many newer vehicles now offer telematics programs where you can download an app to start my car and monitor driving habits. These programs track your driving behavior and can lead to significant discounts if you drive safely. Check with your insurer to see if this option is available.
5. Maintain a Clean Driving Record
This sounds obvious, but it is worth repeating. Avoid speeding tickets, accidents, and claims whenever possible. A single violation can haunt your rates for three to five years. Safe driving pays off in lower premiums.
6. Ask About Loyalty and Affinity Discounts
Some insurers offer discounts for long-term customers, members of certain organizations, or alumni of specific schools. Always ask your agent about available discounts you might qualify for. You might be surprised by what you find.
Common Mistakes People Make When Insuring a Luxury Sedan
Even thoughtful car owners sometimes make insurance mistakes. Avoiding these pitfalls can save you money and headaches.
Only Buying State-Minimum Coverage
The minimum coverage required by law is often not enough for a luxury vehicle. If you total a Q50, state minimums may not cover the full replacement cost. Full coverage with collision and comprehensive is essential for luxury cars.
Not Reviewing Your Policy Annually
Insurance needs change over time. A policy that made sense three years ago might not be the best fit now. Review your coverage every year and adjust as needed. You might be paying for coverage you no longer require.
Ignoring the Impact of Modifications
Aftermarket upgrades like performance exhausts, upgraded wheels, or custom interiors can increase your insurance cost. Always notify your insurer about modifications. Undeclared changes can void your policy when you need it most.
Dropping Coverage on an Older Car
While it is true that older Q50 models are worth less, dropping all coverage is risky. Liability insurance protects you from lawsuits and major expenses. Keep at least liability and uninsured motorist coverage regardless of the car’s age.
Expert Insights on Luxury Car Insurance
We spoke with insurance professionals who shared their perspective on covering luxury vehicles like the Infiniti Q50.
Focus on the total cost of ownership, says one independent agent. Insurance is just one piece of the puzzle. Maintenance, fuel, and repairs all add up. The Q50 is no exception. Budgeting for insurance early helps you avoid surprises.
Another expert recommends checking safety ratings before buying any luxury car. Vehicles with strong safety scores often qualify for better rates. The Q50 has received solid marks in crash tests, which works in your favor when shopping for coverage.
One more tip from the pros: never lie on your insurance application. Misrepresenting your driving habits or garaging address can lead to denied claims. Honesty always pays off in the long run.
How to Get the Best Insurance Deal for Your Q50
Finding the right policy takes a bit of work, but the savings are well worth the effort. Here is a simple step-by-step approach you can follow.
- Gather your information. Have your driver’s license, vehicle details, and current policy ready.
- Get quotes from at least three companies. Use online tools or work with an independent agent.
- Compare coverage levels, not just prices. A cheaper policy with less coverage is not always the better deal.
- Ask about every available discount. Safe driver, bundling, multi-car, and loyalty discounts can all apply.
- Read the fine print. Understand deductibles, limits, and exclusions before signing.
- Review your policy annually. Adjust coverage as your life changes and your Q50 ages.
Following these steps puts you in a strong position. You will find a policy that balances affordability with solid protection for your luxury sedan.
Is the Infiniti Q50 Worth the Insurance Cost?
This is the real question, isn’t it? The answer depends on your priorities and budget. The Q50 delivers a premium driving experience with its refined interior, powerful engine options, and sharp handling. It holds its value reasonably well compared to some competitors.
Insurance costs are a real consideration. But they are part of the overall ownership picture. If you can manage your premiums through the tips in this article, the Q50 remains an excellent choice for anyone who wants a luxury sedan without the sky-high price tag of a German rival.
Many owners find that the driving pleasure and comfort of the Q50 more than justify the extra insurance expense. It is a car that makes every commute feel special. That value matters beyond just the numbers on a quote sheet.
Also keep in mind that your insurance costs will decrease over time. As the Q50 depreciates, your premiums will naturally drop. Patience and smart coverage choices make the ownership experience much more affordable in the long run.
Final Thoughts
The Infiniti Q50 is a fantastic luxury sedan that deserves the road. But insurance is a necessary part of owning one. The costs are higher than a standard sedan, but they are manageable with the right strategy.
Understand what drives the premiums, take advantage of discounts, and always compare quotes. These simple steps can save you significant money over the years. Knowledge is your best tool when it comes to navigating luxury car insurance.
Whether you drive a brand-new Q50 or a pre-owned model, the tips in this guide apply. Stay proactive, review your coverage regularly, and never settle for the first quote you receive. Your wallet will thank you.
Frequently Asked Questions
Is the Infiniti Q50 more expensive to insure than a BMW 3 Series?
Not necessarily. Insurance rates for the Q50 and BMW 3 Series are quite similar. Both are luxury sedans with comparable repair costs. Your personal factors like driving history and location will have a bigger impact on your rate than the specific brand. Always get quotes for both to see which works better for your situation.
Does the Q50 Red Sport trim cost more to insure?
Yes, the Red Sport 400 typically costs more to insure than the base Q50. The higher horsepower, sport-tuned suspension, and higher price tag all contribute to increased premiums. Performance vehicles generally fall into higher insurance groups, so expect a noticeable difference.
Can I lower my Q50 insurance by installing safety features?
Absolutely. Many insurers offer discounts for advanced safety features like adaptive cruise control, blind-spot monitoring, and collision avoidance systems. Aftermarket anti-theft devices can also help. Contact your insurer to confirm which features qualify for discounts on your specific policy.
How often should I shop for new Q50 insurance?
At least once a year. Insurance rates change frequently based on market conditions and company policies. Reviewing your policy annually ensures you are not overpaying. Major life changes like moving or adding a teen driver also warrant a fresh comparison of quotes.
Are older Q50 models cheaper to insure?
Yes, older model years are generally less expensive to insure. As the vehicle depreciates, the replacement cost drops, which lowers your premium. However, always maintain adequate liability coverage regardless of the car’s age. The Q50’s luxury parts remain costly even in older years.
Will my credit score affect my Q50 insurance rate?
In most states, yes. Insurers use credit-based insurance scores as one factor in setting rates. A higher credit score typically leads to lower premiums. Improving your credit before applying for insurance can result in meaningful savings on your Q50 coverage.