Does Car Insurance Cover Windshield Damage
Yes, car insurance can cover windshield damage, but it depends on your policy type and the cause of the damage. Comprehensive coverage typically includes windshield repairs and replacements, while basic liability plans usually do not. Understanding your car insurance policy helps you avoid unexpected costs and speeds up the insurance claim process when disaster strikes.
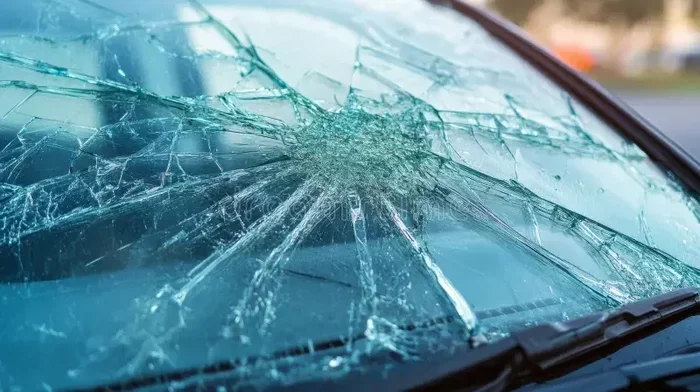
You are driving down the highway. A rock flies up from a truck ahead and hits your windshield. You pull over. There is a crack spreading across the glass. Your mind races. Does car insurance cover windshield damage? The short answer is yes, but the full picture is more nuanced than you might expect.
Windshield damage is one of the most common types of vehicle damage. Rocks, debris, temperature changes, and even accidents can cause chips, cracks, and full breaks. Whether your car insurance policy pays for the repair or replacement depends on the type of coverage you carry, the cause of the damage, and your specific insurance provider terms.
In this guide, we walk you through everything you need to know. We cover what types of insurance pay for windshield damage, how the claim process works, what your deductible means, and how to decide whether to file a claim or pay out of pocket. By the end, you will have a clear picture of your options and feel confident making the right decision for your vehicle insurance needs.
Key Takeaways
- Comprehensive Coverage Pays: Most full-coverage policies include windshield damage under comprehensive insurance.
- Deductibles Apply: You may need to pay an auto insurance deductible before your insurer covers the rest.
- Small Cracks Can Be Repaired: Minor chips and cracks often qualify for free or low-cost windshield crack repair.
- Claims Affect Your No Claim Bonus: Filing a windshield claim can reduce your no claim bonus and raise future premiums.
- Zero Deductible Options Exist: Some insurers offer zero deductible windshield coverage as an add-on benefit.
- Prevention Helps: Using protective films and practicing safe driving reduces windshield damage risk.
📑 Table of Contents
- What Does Car Insurance Cover for Windshield Damage?
- How the Windshield Insurance Claim Process Works
- Deductibles and Costs: What You Need to Know
- How Windshield Damage Affects Your Insurance Premiums
- Preventing Windshield Damage
- When to Replace vs. Repair Your Windshield
- Expert Insights on Windshield and Insurance
- Key Takeaways
- Frequently Asked Questions
- Conclusion
What Does Car Insurance Cover for Windshield Damage?
The answer starts with understanding your policy type. Not all car insurance is the same. Different levels of coverage handle different kinds of damage. Here is a breakdown of how each type of policy typically handles windshield issues.
Liability Coverage and Windshield Damage
Liability coverage is the most basic form of auto insurance. It pays for damage you cause to other people or their property in an accident. However, it does not cover damage to your own vehicle. If a rock hits your windshield while you are driving, liability coverage will not pay for the repair. This is a common point of confusion for many policyholders.
Comprehensive Coverage and Windshield Damage
Comprehensive coverage is the key player when it comes to windshield damage. This type of vehicle insurance covers non-collision damage. That includes rocks, falling branches, vandalism, theft, and weather events like hail storms. If your windshield gets cracked by a flying stone, comprehensive coverage typically steps in to pay for the repair or replacement.
Most full-coverage policies bundle comprehensive coverage with collision coverage. Collision pays for damage from accidents involving another vehicle or object. Comprehensive handles everything else. Together, they give you broad protection for your car. If you only carry liability insurance, you will likely pay for windshield repairs entirely on your own.
Collision Coverage and Windshield Damage
Collision coverage applies when your car is damaged in an accident with another vehicle or object. If you hit a guardrail and your windshield shatters, collision coverage would apply. But if a bird flies into your windshield while parked, collision coverage would not cover it. That falls under comprehensive.
How the Windshield Insurance Claim Process Works
Filing a claim for windshield damage is straightforward, but there are steps you should follow carefully to ensure a smooth experience. Here is how the process typically works.
Step 1: Assess the Damage
First, check the damage carefully. Is it a small chip or a long crack? Small chips under two inches often qualify for simple repair. Longer cracks or damage in the driver’s line of sight usually require a full replacement. Take clear photos of the damage from multiple angles. This documentation will be essential for your car insurance claim.
Step 2: Contact Your Insurance Provider
Call your insurance provider as soon as possible. Report the damage and let them know you want to file a claim. They will ask for details about how the damage happened and may request the photos you took. Some insurers also offer a mobile app that lets you file claims directly from your phone.
Step 3: Get an Estimate
Your insurer may ask you to get a repair or replacement estimate. Many companies have preferred repair shops. You can also choose your own shop in most cases. The estimate will show the cost of the repair or full replacement. This number is important because it determines whether filing a claim makes financial sense.
Step 4: Approval and Repair
Once your claim is approved, the repair or replacement gets scheduled. If you chose a preferred shop, the process is usually fast. The shop communicates directly with the insurance company. You pay your deductible, and the insurer pays the rest. Most windshield replacements take less than two hours to complete.
Deductibles and Costs: What You Need to Know
Your auto insurance deductible is the amount you pay out of pocket before your insurance kicks in. Deductibles vary by policy and provider. Common deductible amounts range from $250 to $1,000 for comprehensive coverage.
Here is a simple example. Say your windshield replacement costs $400. Your deductible is $500. In this case, it does not make sense to file a claim. You would pay the full $400 yourself. But if the replacement costs $1,200 and your deductible is $500, your insurer pays $700 and you pay $500. Filing the claim saves you money.
Some insurers offer a zero deductible windshield option. This means you pay nothing out of pocket for windshield claims. This add-on is especially valuable because windshield repairs and replacements happen frequently. The small extra premium can save you significant money over time.
When Filing a Claim Makes Sense
- The repair or replacement cost exceeds your deductible.
- The damage is in the driver’s direct line of sight.
- You have a zero deductible windshield add-on.
- The damage was caused by a covered event like hail or a falling tree.
When to Pay Out of Pocket
- The repair cost is lower than your deductible.
- The damage is minor and a simple chip repair costs under $100.
- You are close to your policy renewal date and do not want to risk losing your no claim bonus.
How Windshield Damage Affects Your Insurance Premiums
One of the biggest concerns drivers have is whether filing a windshield claim will raise their rates. The answer depends on several factors.
In many cases, a single comprehensive claim for windshield damage does not significantly increase your premium. This is because comprehensive claims are often considered non-fault events. Unlike accident claims where you were at fault, windshield damage from a rock or debris is usually nobody’s fault.
However, multiple claims within a short period can trigger a rate increase. Insurers view frequent claims as a sign of higher risk. If you file several windshield claims in one year, your insurance premium could go up at renewal time. This is why it is wise to weigh the cost of repair against the potential premium increase before filing.
Your no claim bonus is another important factor. This is a discount you earn for each claim-free year on your policy. Filing a windshield claim can reduce or reset your no claim bonus. Over time, this discount can save you hundreds of dollars. Losing it even once may not be worth a small repair.
Preventing Windshield Damage
Prevention is always better than repair. While you cannot control every situation on the road, there are steps you can take to reduce the risk of windshield damage.
Maintain Safe Following Distance
Keep a safe distance from trucks and vehicles carrying loose cargo. Rocks and debris fly up from the back of vehicles, especially on highways and gravel roads. The further back you stay, the lower your risk.
Use Windshield Protection
Consider applying a 3M anti glare film for car windshield or a similar protective film. These films add a layer of strength to your glass. They can help prevent small chips from turning into full cracks. They also reduce glare from the sun, which improves visibility and reduces eye strain during long drives.
Another option is a windshield sun shade or UV-protective cover. Extreme heat causes existing chips to expand and cracks to spread. Parking in the shade or using a sun shade helps protect your glass from thermal stress.
Avoid Driving in Hazardous Conditions
- Stay off the road during severe hailstorms.
- Avoid driving closely behind construction vehicles.
- Be extra cautious on gravel and dirt roads.
- Pull over safely during heavy debris zones.
Regular Car Glass Maintenance
Keep your windshield clean and free of buildup. Dirt and grime can make small chips harder to spot. Over time, these tiny chips grow into cracks. Regular cleaning helps you catch damage early. You can also inspect your windshield weekly for any signs of stress or damage. Addressing small issues quickly prevents costly replacements later.
Removing unwanted things from car glass regularly also helps maintain clarity and structural integrity. Use proper glass cleaners and microfiber cloths to avoid scratching the surface.
When to Replace vs. Repair Your Windshield
Not all windshield damage requires a full replacement. Understanding the difference saves you money and time.
Repairable Damage
Small chips and cracks under three inches are usually repairable. Repair involves injecting a clear resin into the damaged area. The resin cures and bonds with the glass. This restores structural integrity and prevents the crack from spreading. A repair typically costs between $50 and $100 and takes about 30 minutes.
Replaceable Damage
Damage is generally considered replaceable when:
- The crack is longer than three inches.
- The damage is in the driver’s direct line of sight.
- Multiple cracks or chips are scattered across the windshield.
- The damage extends to the edges of the glass.
- The glass has shattered or is significantly weakened.
A full replacement typically costs between $200 and $500 depending on your vehicle make and model. Luxury or specialty vehicles with advanced driver assistance systems (ADAS) may cost more because the sensors near the windshield need recalibration after replacement.
Expert Insights on Windshield and Insurance
Insurance experts recommend reviewing your policy details at least once a year. Make sure you understand your coverage limits, deductible amounts, and any add-ons like zero deductible windshield protection. Small gaps in coverage can lead to surprising out-of-pocket costs when damage occurs.
Experts also advise keeping your insurer’s claims hotline number saved in your phone. After an incident, quick action leads to faster processing and better outcomes. Delaying a claim can sometimes complicate the process or raise questions about the cause of damage.
One often overlooked tip is to check whether your policy includes roadside assistance. Many comprehensive plans do. This benefit can cover towing to a repair shop and even arrange for a rental vehicle while your windshield is being replaced. It is a valuable perk that adds peace of mind, especially during long trips or in unfamiliar areas.
Key Takeaways
- Comprehensive Coverage Is Essential: It is the primary type of coverage that pays for windshield damage from non-collision events.
- Deductibles Determine Your Out-of-Pocket Cost: Always compare the repair cost to your deductible before filing a claim.
- Small Damage Is Often Repairable: Chips and small cracks can usually be fixed quickly and affordably.
- Claims Can Affect Your No Claim Bonus: Consider the long-term cost of losing your discount before filing.
- Prevention Reduces Risk: Protective films, safe driving habits, and regular inspections help keep your windshield intact.
- Replacement Is Necessary for Severe Damage: Large cracks, edge damage, and shattered glass require a full replacement.
Frequently Asked Questions
Does liability car insurance cover windshield damage?
No, liability insurance does not cover damage to your own vehicle. It only pays for damage you cause to others. Windshield damage to your car falls under comprehensive or collision coverage, depending on how it happened.
Will filing a windshield claim raise my insurance rates?
Usually, a single comprehensive windshield claim does not raise rates significantly because it is considered a non-fault event. However, multiple claims or a history of frequent claims can lead to premium increases at renewal time.
How long does a windshield claim take to process?
Most windshield claims are processed within a few days. Simple repairs can often be completed the same day. Full replacements typically take one to two hours at the repair shop once the claim is approved.
Can I choose my own repair shop for a windshield claim?
Yes, in most cases you can choose your preferred repair shop. Some insurers have partnered shops that offer direct billing, which simplifies the process. However, you are generally free to select any reputable shop.
What is a zero deductible windshield add-on?
A zero deductible windshield add-on is an optional coverage that removes your deductible for windshield claims. This means your insurer pays the full cost of repair or replacement, and you pay nothing out of pocket. It is a small extra cost that can save significant money over time.
Does car insurance cover windshield damage from weather events?
Yes, comprehensive coverage typically covers windshield damage caused by weather events such as hail storms, falling tree branches, and severe windstorms. These are considered non-collision events and fall squarely under comprehensive protection.
Conclusion
So, does car insurance cover windshield damage? The answer is yes, but with important conditions. Your coverage type, deductible amount, and the cause of the damage all play a role. Comprehensive coverage is the key that unlocks windshield protection for most drivers. Without it, you are left paying for repairs and replacements yourself.
Understanding your policy empowers you to make smart decisions. You can weigh the cost of a claim against potential premium increases. You can decide when to repair and when to replace. You can take preventive steps to protect your windshield before damage ever occurs.
Take a few minutes today to review your car insurance policy. Check your coverage type, your deductible, and any add-ons you may have. If you do not carry comprehensive coverage, consider adding it. The peace of mind it provides is well worth the extra cost. Your windshield protects you on every drive, and your insurance should protect it in return.