Does Car Insurance Cover Scratches and Dents on Your Car
Car insurance may cover scratches and dents, but it depends on your policy type, the cause of damage, and your deductible amount. Comprehensive coverage typically handles non-collision damage like vandalism or hail, while collision coverage applies to accident-related dents. Understanding your auto insurance policy helps you decide whether filing a claim is worth the cost.
You just walked to your car and spotted a fresh scratch across the door. Or maybe you returned to find a nasty dent on your bumper. The first thought that hits most people is the same: does car insurance cover scratches and dents? The answer is not a simple yes or no. It depends on several factors, including your policy type, the cause of the damage, and your deductible amount.
Understanding what your auto insurance policy actually covers can save you from surprise bills or unnecessary premium increases. In this guide, we break down everything you need to know about filing a claim for scratches and dents. We cover the types of coverage, when it makes sense to file, and how to get the best outcome from your insurance claim.
Let us be honest. Most people do not read their insurance policy cover page to cover page. But knowing the basics can make a huge difference when you face unexpected vehicle damage. Whether it is a shopping cart dent in a parking lot or a key scratch from a jealous neighbor, this article has you covered.
Key Takeaways
- Coverage depends on policy type: comprehensive and collision policies handle different kinds of scratches and dents.
- Deductible matters: if repair costs are below your deductible, paying out of pocket makes more sense.
- Small claims can raise premiums: filing too many claims may increase your insurance premium over time.
- Paintless dent repair is affordable: this quick fix can save you money compared to traditional body shop repairs.
- Document everything: photos and police reports strengthen your car insurance claim process.
- Not all damage is covered: wear and tear, intentional damage, and pre-existing issues are typically excluded.
- Compare repair costs first: get quotes before deciding whether to file a claim with your insurer.
📑 Table of Contents
- Types of Car Insurance That May Cover Scratches and Dents
- When Does Car Insurance Cover Scratches and Dents
- The Insurance Claim Process for Scratch and Dent Damage
- Should You File a Claim for Scratches and Dents
- Types of Scratch and Dent Repair
- How to Prevent Scratches and Dents on Your Car
- Expert Insights on Scratch and Dent Claims
- Common Mistakes Drivers Make with Scratch and Dent Claims
- Frequently Asked Questions
- Final Thoughts
Types of Car Insurance That May Cover Scratches and Dents
Not all car insurance policies are the same. Some cover scratches and dents, while others do not. Let us look at the main types of coverage that come into play when your car suffers body damage.
Comprehensive Coverage
Comprehensive coverage is your go-to for non-collision damage. Think of it as the catch-all policy for things that happen to your car outside of a crash. This includes vandalism, theft, falling objects, weather damage, and animal encounters. If someone keyed your car or a tree branch fell on your hood, comprehensive coverage typically steps in.
Here is what comprehensive coverage usually handles:
- Vandalism and malicious scratches
- Falling objects like tree branches or hail
- Weather-related damage such as hail dents
- Animal damage, including collisions with deer
- Fire damage to your vehicle
- Theft-related damage
If you live in an area prone to hailstorms or have experienced car vandalism before, comprehensive coverage is essential. It is one of the most common ways drivers get their scratches and dents repaired through insurance.
Collision Coverage
Collision coverage kicks in when your car hits something or something hits your car. This includes accidents with other vehicles, hitting a guardrail, or rolling your car. If you backed into a pole and dented your bumper, collision coverage has you covered.
Collision coverage applies to:
- Accidents with other vehicles
- Single-car accidents like hitting a curb or pole
- Rolling or flipping your vehicle
- Damage from hit-and-run incidents
Keep in mind that collision coverage requires you to pay a deductible first. The deductible is the amount you pay out of pocket before your insurer covers the rest. Deductibles typically range from $250 to $1,000, though some policies go higher. If the repair cost is close to or below your deductible, filing a claim may not make financial sense.
Third-Party Liability Coverage
Third-party liability coverage does not cover your own scratches or dents. It covers damage you cause to someone else’s property or vehicle. So if you accidentally scrape another car in a parking lot, this coverage pays for their repairs, not yours.
However, if the other driver is at fault and has proper coverage, their insurance may pay for the damage to your car. This is where the claim process gets a bit more involved, but it can save you money on your own deductible.
When Does Car Insurance Cover Scratches and Dents
Knowing which coverage applies is only half the battle. The next question is when does your policy actually pay out for scratches and dents? Let us walk through the common scenarios.
Covered Scenarios
Your insurance is most likely to cover damage in these situations:
- Vandalism: someone deliberately scratched or dented your car. This falls under comprehensive coverage in most policies.
- Weather damage: hail, falling branches, or ice can cause multiple dents. Comprehensive coverage handles these claims.
- Accidents: if you hit another car or object and caused damage to your own vehicle, collision coverage applies.
- Animal collisions: hitting a deer or other animal can cause significant body damage. Comprehensive coverage typically covers this.
- Falling objects: a shopping cart rolling into your car in a parking lot or debris from a truck falling onto your hood.
Not Covered Scenarios
Insurance companies do not cover everything. Here are common situations where your claim will likely be denied:
- Wear and tear: normal aging, sun damage, or minor surface scratches from everyday use are not covered.
- Intentional damage: if you damage your own car on purpose, the claim will be denied.
- Pre-existing damage: damage that existed before your policy started is not covered.
- Mechanical failure: scratches or dents resulting from a mechanical breakdown are usually excluded.
- Driving without a license: most policies void coverage if you were driving illegally at the time of damage.
Always read your policy documents carefully. If you are unsure whether a specific type of damage is covered, call your insurance agent before filing a claim. A quick phone call can save you from a denied claim and wasted time.
The Insurance Claim Process for Scratch and Dent Damage
Filing a claim for scratches and dents is not as complicated as it sounds. But it does require some patience and attention to detail. Here is how the process typically works.
Step 1: Document the Damage
Before you do anything else, document everything. Take clear photos of every scratch and dent from multiple angles. Capture the surrounding area too. This evidence is crucial when you file your claim. If someone witnessed the damage, get their contact information.
If the damage happened in a parking lot and you have a dashcam or nearby security camera footage, save that footage immediately. The more evidence you have, the stronger your claim will be.
Step 2: File a Police Report (If Applicable)
For vandalism or hit-and-run incidents, file a police report right away. Many insurance companies require a police report before they process your claim. Even if the police cannot find the perpetrator, having an official report strengthens your case.
Step 3: Contact Your Insurance Company
Call your insurance provider or use their app to file the claim. Be ready to provide your policy number, photos, and a description of what happened. The sooner you file, the better. Most policies have time limits for reporting claims.
Step 4: Get an Estimate
Your insurer will likely require an estimate from a licensed repair shop. Some companies have preferred shops you must use, while others allow you to choose. Get at least two estimates to understand the full repair cost. You can also explore DIY car diagnostics to understand the extent of the damage before visiting a shop.
Step 5: Pay Your Deductible and Get Repairs
Once the claim is approved, you pay your deductible amount. The insurer pays the rest directly to the repair shop or reimburses you. The repair timeline varies depending on the severity of the damage and the shop’s workload.
Should You File a Claim for Scratches and Dents
This is the million-dollar question. And the answer is: it depends. Filing a claim is not always the smartest move, even when your policy covers the damage.
When Filing Makes Sense
Filing a claim makes sense when:
- The repair cost is significantly higher than your deductible.
- The damage is extensive and affects safety features like sensors or cameras.
- The damage was caused by a major event like a storm or accident.
- You have a low deductible and the repair cost far exceeds it.
For example, if a hailstorm causes $2,000 in dents and your deductible is $500, filing a claim is a smart move. You pay $500 and your insurer covers the remaining $1,500.
When Paying Out of Pocket Is Better
Paying for repairs yourself is often better when:
- The repair cost is close to or below your deductible.
- The damage is minor and does not affect safety or function.
- You have a history of frequent claims, which could raise your rates.
- The claim could trigger an insurance premium increase that costs more than the repair over time.
Here is a quick comparison to help you decide.
| Scenario | Repair Cost | Deductible | Claim Worth It? |
|---|---|---|---|
| Small scratch, touch-up paint needed | $150 | $500 | No, pay out of pocket |
| Hail dents on roof and hood | $2,500 | $500 | Yes, file a claim |
| Bumper dent from parking lot | $600 | $500 | Borderline, compare options |
| Key scratch down the side panel | $800 | $1,000 | No, pay out of pocket |
| Multi-panel damage from accident | $4,000 | $500 | Yes, file a claim |
As a rule of thumb, if the repair cost is at least three times your deductible, filing a claim usually makes financial sense. Anything less, and you are better off paying for the repairs yourself.
The Hidden Cost of Filing Claims
Many drivers do not realize that filing a claim can have long-term financial consequences. Insurance companies track your claim history. Multiple claims within a few years can signal high risk, leading to higher premiums at renewal time. In some cases, a single claim can increase your annual premium by 20% to 40%.
Over three to five years, that premium increase can easily exceed the cost of the repair. This is why many experts recommend thinking twice before filing a claim for minor damage.
Types of Scratch and Dent Repair
If you decide not to file a claim or your deductible is too high, you still have options for getting your car looking great. Understanding the repair methods helps you make informed decisions.
Paintless Dent Repair
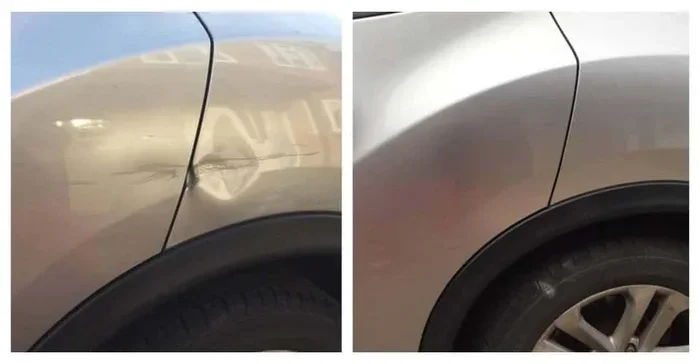
Paintless dent repair, or PDR, is a popular method for removing dents without damaging the original paint. Technicians use specialized tools to gently massage the dent from behind the panel. This method is fast, affordable, and preserves your factory paint finish.
PDR works best for:
- Small to medium dents with no paint damage
- Hail damage
- Door dings from parking lot incidents
- Minor creases from minor impacts
The cost of PDR is typically 50% to 70% less than traditional body shop repairs. For minor dents, it is often the best option available.
Traditional Body Shop Repair
For deeper scratches or dents with paint damage, traditional body shop repair is necessary. This process involves sanding, filling, priming, painting, and clear coating the affected area. It is more expensive and time-consuming than PDR, but it produces excellent results for severe damage.
Traditional repair is needed when:
- The paint is cracked or removed
- The dent is deep and cannot be massaged out
- Rust has started to form on the exposed metal
- Multiple panels need repair or matching
DIY Scratch Repair Kits
For minor surface scratches, DIY scratch repair kits can be a cost-effective solution. These kits include touch-up paint, clear coat, and polishing compounds. They work well for superficial scratches that have not penetrated the primer layer.
However, be cautious with DIY repairs. Poor application can make the damage more visible or lead to rust over time. For anything beyond a very minor surface scratch, professional repair is recommended.
How to Prevent Scratches and Dents on Your Car
Prevention is always better than repair. While you cannot prevent every scratch or dent, these tips can significantly reduce your risk of vehicle damage.
- Park in covered areas: garages and carports protect your car from falling branches, hail, and vandalism.
- Avoid tight parking spaces: crowded lots increase the risk of door dings and scratches from other cars.
- Use car covers: a quality car cover shields your vehicle from weather damage and UV rays.
- Install paint protection film: PPF on high-impact areas like the front bumper and hood adds a protective layer.
- Keep distance from other vehicles: maintaining space while driving reduces the chance of minor collisions.
- Be mindful of shopping carts: park away from cart corrals in parking lots.
Taking these simple precautions can save you hundreds of dollars in repair costs over the life of your vehicle. A little effort today can prevent a lot of headaches tomorrow.
Expert Insights on Scratch and Dent Claims
We spoke with several insurance professionals to get their perspective on scratch and dent claims. Here are the key insights they shared.
File early, not late. Most insurers have a time limit for filing claims, usually within 30 to 90 days of the incident. Delaying can result in a denied claim. If you notice damage, document it and report it promptly.
Get multiple repair estimates. Insurance adjusters sometimes lowball the estimate. Having your own independent estimate gives you leverage to negotiate a fair payout. If you are unsure about the damage severity, consider getting a professional car dent repair assessment before filing.
Understand your policy limits. Every policy has limits on how much the insurer will pay for a claim. If the repair cost exceeds your policy limit, you may need to pay the difference. Review your policy limits annually to ensure adequate coverage.
Consider the long-term impact. As mentioned earlier, claims can affect your premium for years. Weigh the short-term benefit of a free repair against the long-term cost of higher premiums. Sometimes the smartest financial move is to pay for minor repairs yourself and save your claim history for major incidents.
Common Mistakes Drivers Make with Scratch and Dent Claims
Avoid these common pitfalls that can cost you time, money, and peace of mind.
- Waiting too long to file: delays can result in claim denial. Report damage as soon as possible.
- Not documenting damage properly: blurry or incomplete photos weaken your claim. Take clear, well-lit photos from every angle.
- Repairing before the adjuster visit: some insurers require the adjuster to see the damage first. Always confirm before scheduling repairs.
- Choosing the cheapest repair shop: low-cost shops may use inferior parts or poor techniques. Choose a reputable shop with certified technicians.
- Ignoring small damage: small scratches can lead to rust if left untreated. Address minor damage promptly to prevent bigger problems.
- Assuming all damage is covered: read your policy carefully. Not every type of damage qualifies for coverage.
These mistakes are easy to avoid with a little research and patience. Taking the right steps from the start ensures a smooth claim process and a fair payout.
Frequently Asked Questions
Does car insurance cover scratches from a keying incident?
Yes, scratches from keying are typically covered under comprehensive coverage because they are considered vandalism. However, you will need to file a police report and provide evidence of the damage. Your deductible will apply, so if the repair cost is below your deductible, it may not be worth filing a claim.
Will filing a scratch or dent claim increase my insurance premium?
It can. Filing a claim may cause your premium to increase at your next renewal, especially if you have filed multiple claims in the past. The increase depends on your insurer, your claim history, and the severity of the claim. For minor damage, paying out of pocket is often the smarter choice.
How long does it take to process a scratch or dent claim?
Most claims are processed within 2 to 4 weeks. Simple claims with clear evidence can be resolved faster. Complex claims involving multiple panels or disputed liability may take longer. Your insurance adjuster can give you a more accurate timeline based on your specific situation.
Can I choose my own repair shop for scratch and dent repairs?
In most cases, yes. Some insurers have preferred networks, but many allow you to choose any licensed repair shop. If your insurer has a preferred shop, you can still request to use your own shop. You may need to cover any cost difference if your chosen shop charges more than the insurer’s estimate.
Is paintless dent repair covered by insurance?
Yes, if the damage is covered by your policy. Paintless dent repair is a recognized repair method, and most insurers will pay for it as part of your claim. PDR is often cheaper than traditional repair, which can mean a lower payout and less impact on your deductible.
What should I do if my claim for scratches or dents is denied?
If your claim is denied, review the denial letter to understand the reason. Common reasons include pre-existing damage, wear and tear, or insufficient documentation. You can appeal the decision with additional evidence. If the appeal is unsuccessful, consider getting an independent assessment or consulting an insurance ombudsman for guidance.
Final Thoughts
So, does car insurance cover scratches and dents? The short answer is yes, but with conditions. Your auto insurance policy type, the cause of the damage, and your deductible all play a role in determining whether you get paid. Comprehensive coverage handles most non-accident damage, while collision coverage applies to accident-related dents.
The key is to understand your policy before you need it. Review your coverage limits, know your deductible amount, and familiarize yourself with the claim process. When damage occurs, document everything, file promptly, and weigh the financial impact of filing versus paying out of pocket.
Scratches and dents are an unfortunate reality of car ownership. But with the right insurance coverage and a smart approach to claims, you can get your car back to looking its best without breaking the bank. Take the time to understand your policy today, and you will be glad you did when the unexpected happens tomorrow.